Warning: Undefined array key "url" in /var/www/moneyandfreedom.com/public_html/wp-content/plugins/seo-by-rank-math/includes/modules/schema/snippets/class-author.php on line 41
Loss Aversion: Why Money Stress Hits Even When You Have Millions

Loss Aversion: Why Money Stress Hits Even When You Have Millions

A few years ago I lived in a one-bedroom co-op apartment in the middle of Nørrebro in Copenhagen.

Today I live in a house in Cascais, Portugal, with five bedrooms, a pool, a garden and a view of the beach.

There are millions in my name.

And still, money can make me anxious.

It comes down to something we all suffer from, called loss aversion, and that is what this blog post is about.

But first, let me show you my numbers. And why I get so anxious.

My rent is over 6,600 euro a month (about $7,500).

I also have an unexpected tax bill from Denmark, which costs almost another 6,000 euro a month.

On top of that come two private schools, help at home, hobbies and travel.

Our life costs at least 200,000 euro a year. Probably more. 

My kids are used to big houses, pools, private schools and household help.

That is their normal. It is not mine.

My normal was a co-op apartment in Nørrebro.

Over the summer, from May to September, I have no income from courses, and at the same time, spending on travel and entertainment is high.

I have no fixed salary from the fund I run, only a bonus (and so far I have not received one).

My oldest son could feel that something was changing this summer. I no longer say yes to every suggestion.

Every night he had trouble falling asleep, and he asked:

“Mom, I’m afraid we’re going to lose our house and have to move.”

He is experiencing what lies behind money anxiety for so many people: loss aversion.

A huge, fat fear of losing.

And it rubs off. A moment later, I couldn’t sleep either.

What Is Loss Aversion?

Loss aversion is a psychological phenomenon where the pain of losing something feels bigger than the joy of winning something equivalent.

Losing $1,000 hurts more than winning $1,000 feels good.

It is instinctive.

Our ancestors who were most alert to threats survived longer than those who didn’t.

But today it makes us needlessly worried.

We focus more on what we might lose in the future than on what we could achieve.

It can make us overestimate risks, underestimate opportunities and make decisions out of fear rather than long-term goals.

Here Is How You Overcome It

1. Get Clear on What Money Is For

Ask yourself what the money is for.

Be specific and write it down.

Not a vague feeling like “financial freedom”, but something concrete you can hold yourself to.

This does two things.

A. When you have concrete goals, you can calculate what they cost.

A vague worry becomes a concrete problem with a concrete solution.

B. Money stops feeling like a monster.

It becomes a tool with a job to do.

2. Stop Comparing

Most people always want more, because they compare themselves with others.

Nothing new there.

We have always measured ourselves against others. It is another instinct from prehistoric times.

We need to belong to the group.

The one who got thrown out of the group did not survive.

So we tend to look around and try to fit in, or better still, to be recognized, maybe even admired.

With social media, the basis for comparison is endless, and it is systematically skewed toward the most visible and wealthy versions of other people’s lives.

So what do you do?

Start by noticing what makes you more anxious without making you any wiser.

Stop following the people who make you feel behind.

Don’t go where you get a knot in your stomach.

Don’t check what other people’s houses cost, unless you are specifically gathering information to set a money goal.

Your financial life is not a race.

It is a private project, and you decide what you want to build.

3. Tell Useful Worries From Useless Ones

Useful worries point to something real that you can act on.

If you have no buffer and your job feels insecure, the anxiety is telling you something true:

You need to build savings.

Listen to it and do something about it.

Useless worries, on the other hand, are background noise.

They don’t point to anything specific and they don’t lead to action.

They just drain your energy.

And you know what? By far most of the financial stress we walk around with is useless.

The antidote is not more money.

The antidote is clarity.

You need clarity on what you fear, and clarity on what your plan actually is.

Here are two practical exercises that can give you the overview you need to fight the anxiety that comes from loss aversion.

4. Exercise: Exaggerate Your Fear

The Stoics had an exercise they called negative visualization.

They deliberately imagined losing the things they depended on to test their assumptions about what they actually need.

Try it with money.

Ask yourself, honestly, what would happen if the scenaria you fear most came true.

For example: “If I lost my job and my income for a year, what would I do?”

“What if the stock market fell 70% and did not recover for a year?”

What is the worst that could happen?

What would you actually do if it happened?

How realistic is it that it would happen?

5. Make a Plan

Now that you know what you want and what you fear, you are well equipped for the next step.

The next step is to make a plan.

What if?

Yes, what if the stock market falls?

Keep a cash reserve, so you don’t have to sell any of your principal for a year.

What if you lose your job?

Keep a cash reserve.

In fact, most of the financial worries I can think of can be solved with savings.

How Did the Exercises Go for Me?

I originally got hooked on investing when I was a mom who had just lost her job.

I lived in a small apartment in Nørrebro in Copenhagen with a baby and a toddler.

I was desperate to create a good life for my boys.

When I ask myself what matters most and what I want my money to do, I always land on my two boys, and the life I want to give them.

The goal was:

A. A house or apartment with a bedroom for each of us in a quiet area, so we sleep well 

B. Good schools

C. Practical things to make everyday life easier as a mom. Really ordinary things like a washing machine, a dishwasher, cleaning help and a car that can drive us from A to B.

D. Time. I wanted time to be there for my boys when they needed me

The dream was never a Lamborghini.

The dream was never a gigantic house with a pool, although that is nice too.

What About the Comparison?

I don’t care about people on Instagram, and my kids don’t have social media, but we live somewhere where people are very rich.

When I drop my kids off at the private school, I see the other parents driving Porsches, Land Rovers and yes, Lamborghinis.

I drive a 7-year-old Jeep Renegade with scratches in the paint.

When I show up for parent coffee, I carry a leather belt bag with no visible brand.

I call it my dog-walker bag. (Super practical. There is room for keys and a phone, and it doesn’t fall to the ground when I have to pick up dog poop.)

The other moms carry Louis Vuitton.

My oldest son complains that we “only” travel to Denmark twice a year and for skiing (not Denmark) in the winter. 

“I have never been to Bali or Japan,” he says, and adds: “My friends travel at least 4 times a year. And to exciting places.”

And the final blow: “Why do I have to take out my own plate? Why do I have to learn to cook? Milo and Vincent have a maid and a chef.”

My son wants to fit in at school. He wants to live like the others.

We are actually well off, but poor compared with people like Cristiano Ronaldo.

My son feels that, and it creates money anxiety for him.

The Nightmare Scenario

What would I do if, for some absurd reason, I never earned another penny?

I have lived on a rock before, and I could easily do it again.

As long as I can read good books and write my blog posts, I’ll have a party in my head.

But I want to give my two kids stability.

With the money we have today, we could probably stay where we are for five years.

In five years, my boys will be 15 and 18. By then, I think I can say I managed the job of giving them a secure childhood pretty well.

My oldest son talks about going to college in the US. Harvard or Yale.

“Vincent is going to,” he says.

Okay, kid. Vincent is 12.

The Plan

I float the idea that there are some pretty good universities in Denmark.

Because maybe.

In the nightmare scenario where I never earn money again, my son has to move back to Denmark and continue his studies there.

If we had to move into an apartment in five years, we would.

As I tell my son when he can’t sleep:

“We don’t have to move right now. But if we ever have to, we’ll make it cozy no matter where we live. What matters most is the three of us, and that we enjoy each other’s company. We will figure that out in an apartment too.”

But it probably won’t get to that. 

It is only the worst-case scenario, and the best part is that the worst case is not that bad at all.

If you want to learn how to invest, download my e-book here. It only costs your email.
Buffett’s Goal Setting Exercise Only Works This Way

Buffett’s Goal Setting Exercise Only Works This Way

My youngest son and I were going to have some quality time.

“Write down your 25 most important goals,” I said. Because that is the kind of stuff I do for fun on a Sunday.

No Legos. Goal Setting. 

“Why?” he asked. 

He is too little to understand, but between you and me: because I had remembered Warren Buffett’s two-list technique for goal setting and wanted to practice it.

I’ll explain in a moment how it works – or rather how it doesn’t work.

I just told my son the simple version:

“Just imagine a genie comes out of the bottle. What 25 things would you want to happen?”

But for you, the grown-up, here is the story behind it.

Buffett’s Goal Setting Exercise

The exercise for focused goal setting is well known.

The story first showed up with the blogger Scott Dinsmore, back in 2011.

Supposedly he had met someone who knew one of Buffett’s pilots.

It went like this.

Buffett asks his pilot to write down his 25 most important career goals. Then he asks him to circle the 5 most important.

Now the pilot has two lists.

The 5 he circled. And the 20 he did not.

The pilot says he will start on the 5 right away.

The other 20 he likes too, so he will get to them along the way, whenever he can.

Here Buffett stops him.

“No. You’ve got it wrong. Everything you didn’t circle just became your avoid-at-all-costs list. They get no attention until you’ve succeeded with your 5.”

The point is simple.

The 20 goals are not “later.”

They are exactly what steals your time from the 5 that matter.

There is a sad footnote, by the way.

The exercise did not go so well for Scott Dinsmore.

He died in 2015, in an accident on Kilimanjaro.

You cannot help but think: maybe Kilimanjaro should have been on his own avoid-at-all-costs list.

Then It Went Wrong

Okay, back to a cozy Sunday morning with my son.

My own goal setting quickly turned into a mess.

Half an hour later I was more confused than before I started.

“Take the boys to Disneyland” sat right next to “grow the fund to 100 million and beat the index.”

How do you weigh a trip to Disneyland against the fund’s return over ten years?

You cannot. And if I only kept the 5 most important, I would turn into a workaholic and never do anything fun with my children. I sat there puzzling over it. 

How to Make It Work

Here is the problem. I had mixed everything together.

Short term and long term.

Personal and career.

Big and small.

All in one pile.

And that is exactly the trap. When your goal setting mixes timeframes and areas of life, you cannot compare the things.

You have to choose one area. And one timeframe.

Not “my 25 goals,” but “my most important career goal for the coming year.”

It dawned on me that I first have to find categories, and they are easy.

For me they are: my work (including the fund and content like this blog post), family, and my own happiness.

As my coach says: “If it does not either move the fund forward, help you raise the boys, or make you happy, it has to go.”

Under each category, I now make the two lists.

And they have to be made for the long term and the short term.

You zoom out, and you zoom in.

Only then does it make sense to choose the 5 and forget the rest.

A goal-setting exercise that mixes everything leaves you more lost than when you started.

Focus is the real secret of goal setting.

It is not writing everything down. It is choosing what you want to be good at, before you even start listing.

My Son’s List

And my son? Here is what he came up with, exactly as he wrote it.

1. Go to Cascais Shopping.
2. Go somewhere it snows for Christmas.
5. Get a new water bottle for Christmas.
6. Go to New York.
7. Disneyland.
8. Get Netflix back.

Yes, he skipped 3 and 4.

And no, he never made it to 25. Somewhere between New York and a water bottle he looked up and said:

“Mom, there’s nothing left in my brain.”

Maybe he was closer to the point than I was.

Most of us do not have 25 important goals.

We have a few that mean everything. And then a long row of water bottles.

The art is knowing the difference.

If you want to learn how Warren Buffett invests, you are welcome to download my free e-book here.

The Different Investment Strategies and Why Value Investing Wins

The Different Investment Strategies and Why Value Investing Wins

There are many different investment strategies for putting your money to work: growth, value, penny stocks, dividends, momentum, index funds.

There are so many that it’s easy to get confused if you don’t have a clear view of them.

When I talk to other investors, I often notice that in the same conversation they mix up different strategies without realizing it.

Maybe because they got a “hot tip” from another investor, without knowing that investor follows a completely different strategy with their stocks.

The worst thing you can do is jump blindly from one of these investment strategies to another.

Finding the Right Investment Strategy

A year and a half ago, at the annual meeting of my fund, Grünbaum Value Invest, someone asked me why I hadn’t invested in Rheinmetall.

That’s ammunition, weapons, armored vehicles and air defense.

Just a few years earlier, weapons stocks were almost as off-limits as child labor or tobacco. But the mood had shifted, and shares in weapons manufacturers were soaring. Rheinmetall’s stock had risen more than 1,000%.

Specifically chasing weapons stocks would be a thematic strategy, and that’s not what my fund is mandated to do. My fund invests in value.

And there’s a catch. Once a theme has become a theme, once it’s what everyone is talking about in financial newspapers and podcasts, it’s often already too late.

What does that mean? The stock has become overvalued.

Here’s an overview of the different investment strategies you can choose from:

Momentum

Momentum is one of the more popular investment strategies, and it’s about following the flow.

You buy stocks that have already risen a lot, because you believe the rise will continue. The logic is simple: a stock in motion tends to keep moving.

There’s something appealing about it. You don’t need to understand the company’s financials. You just need to be able to read a price chart and have the courage to jump on the wave.

The downside is even bigger, though. The problem arises when the wave turns.

Momentum is driven by psychology and herd behavior, not by what the company is actually worth. You never really look at the reality behind the business. Does it have profits? Is there growth? Is it a good product? None of that matters in this strategy.

When fear takes over from greed, a momentum stock can fall just as fast as it rose. The higher you fly, the harder you fall, as they say.

You also have to time your exit precisely. When is the party over? No one knows for sure, and many momentum investors end up holding stocks that have dropped 50-70%, because they waited just a moment too long.

Penny Stocks

Penny stocks are shares that trade at very low prices, often in small, unknown companies.

The bait is obvious: people think, “it only costs a few cents, how much lower can it go?”

But a low price says nothing about how cheap a stock really is. If it falls to zero, you’ve lost 100% of your money, whether you started at a few cents or a few hundred dollars.

What determines whether something is cheap is the relationship between the price and what the company is actually worth, not the number on the price tag.

The upside? I don’t know of one.

The downside? You’re fumbling in the dark with a reckless strategy.

Day Trading

Day trading is a completely different discipline.

Here you buy and sell within the same day, sometimes several times an hour. It relies heavily on technical analysis, reading price charts and reacting to patterns within hours, sometimes minutes.

The upside? If you want fast cash, you’ve made some money before the day is over.

The downsides are many, in my view.

It’s effectively a new full-time job. You have to sit ready and react, and decisions must be made quickly, with no time to think things through properly.

It’s also very risky. Most studies show that the vast majority of day traders lose money over time, and that fees and taxes eat up a large part of any potential return along the way.

Growth Investing

Growth investing is one of the most widespread investment strategies, and here you buy shares in companies that are growing quickly.

Revenue rises sharply year after year, and the market expects that to continue for many years to come.

Think of the big tech companies that many people have profited handsomely from in recent years.

The challenge is that all the future growth is already baked into the price. You’re not paying for what the company is worth today. You’re paying for a story about what it might be worth in ten years.

If that story doesn’t come true, the stock falls hard. The more growth the market has expected, the harder the fall tends to be.

I’ve seen it happen again and again: a beloved growth company disappoints just slightly in a single quarter, and the stock plunges.

That’s naturally the downside.

But there’s a solution. We’ll get to that.

In principle, I have nothing against companies with growth and other healthy numbers on the balance sheet, quite the opposite. What I do have something against is overpriced growth companies.

Dividend Investing

Dividend investing is one of the more defensive investment strategies: choosing companies that pay out part of their profits as a regular dividend, ideally one that grows year after year.

It’s a popular strategy, especially among investors who want an income from their portfolio.

The upside is that you get cash in your account at regular intervals. That can create a sense of security and money to cover expenses.

The downside?

A high dividend isn’t necessarily a sign of health.

Some companies pay dividends even when the business is under pressure, because management is afraid of disappointing shareholders by cutting it. A dividend can therefore camouflage problems instead of revealing them.

Even if nothing is wrong, in most cases a dividend can simply be a sign that the company is very mature and doesn’t have much left to grow into.

If they needed to move into new products, markets, or acquire competitors, they would invest in that instead of paying a dividend to shareholders.

Thematic Investing

Thematic investing is one of the more exciting investment strategies: investing in a trend you believe in, for example artificial intelligence, an aging population, cannabis stocks, or weapons and war. You then find the companies that stand to profit from that trend.

The upside: it’s an appealing idea. You don’t have to choose between individual companies, just between themes.

The challenge is that a good theme doesn’t always mean a good investment.

By the time everyone can see a theme coming, the prices of the obvious companies have often already shot up, long before you discover it yourself.

When I got that question about Rheinmetall, the stock had risen more than 1,000% in a few years. But over the past year it’s more than halved.

I’ve seen a fair number of thematic investments wreck portfolios.

Remember when everyone wanted to invest in cannabis stocks because cannabis was being legalized in several countries?

First, companies specializing in cannabis rose extremely sharply, but then they fell quite quickly by up to 90%, and eight years later they still haven’t returned to their peak.

Special Situations

Special situations are about investing around concrete events: divestitures, spin-offs, or acquisitions.

Here you take advantage of the fact that such events often create a temporary mispricing in the stock, because many investors sell or buy based on rules and index obligations, not the company’s real value.

It’s a niche strategy that requires you to follow corporate events closely and understand how they affect the price.

The upside is supposed to be a high return.

But the downside is significant when, for example, the acquisition doesn’t go through after all. I’ve burned my fingers on that once myself, and decided I’ll never place that kind of bet with my money again.

Passive Investing and Index Funds

Passive investing through index funds is probably the simplest of all investment strategies.

You invest broadly across an entire market without picking individual stocks yourself. You simply buy shares in a fund that tracks one of the broad indices, usually the geographic ones like the S&P 500, the Dow Jones, or perhaps even a global index.

The upside? It requires a minimum of your time, and over time index funds have historically delivered a reasonable return.

The downside? There’s a catch that few people talk about.

When you invest passively, you hand the choice of companies over to the index itself. And the index is typically weighted by size.

That means the more overvalued a company becomes, the larger a share of your index it makes up.

You don’t ask yourself whether you’re paying a fair price for the individual companies. You buy all of it, regardless of price.

That can work fine for many years. But it’s worth knowing that you’re effectively giving up thinking for yourself.

And did you know the Dow Jones index fell 80% in 1929? It took 30 years before it reached the same level again.

As I write this, the US stock market is trading far above the level US stocks reached before the 1929 bubble. And yes, it can happen again.

Value Investing

Of all the investment strategies I’ve described here, value investing is the one I trust the most, and the one I’ve chosen myself.

As a value investor, you choose the companies you invest in yourself. You examine what the company is actually worth, and compare that to the price the stock is trading at.

Warren Buffett described it very precisely: it’s like buying a one-dollar bill for 50 cents.

Here’s why I believe this method is stronger than the others.

1. You invest in substance, not sentiment. Where momentum and day trading are about what other investors are doing right now, value investing is about what the company actually earns, and how solid its business is. You don’t depend on others continuing to believe the story.

2. You have a margin of safety. When you buy something for less than it’s worth, you have a buffer if things don’t go exactly according to plan. Growth investors rarely have that buffer. They’ve paid full price for a perfect future.

3. You stay calm when the market falls. When you know what you own and why you own it, a price drop doesn’t become a reason to panic. On the contrary, it becomes an opportunity to buy more of something good at an even better price. That’s harder to say about a momentum stock that’s just plunged, or a growth stock whose story has suddenly become uncertain.

4. You don’t have to guess at psychology. You don’t need to predict whether other investors will keep being optimistic. You just need to be right about the company’s value, and that’s far easier to assess than the market’s mood.

And then there’s one more thing I appreciate about the method.

When you invest broadly through ETFs or index funds, it’s like going to the supermarket and grabbing everything on the top shelf without looking.

As a value investor, you instead look at what you put in your basket, and you know you can stand behind it.

Which Investment Strategy Should You Choose?

If you ask me, the best method is a blend of value and growth.

The best companies I’ve invested in myself have both solid fundamentals and growth in sales and profits.

What’s the difference between A) an ordinary growth investor and B) a value investor with a taste for growth?

The difference is that as a value investor, I always look at what the company is actually worth. Pure growth stocks don’t necessarily do that.

Are there growth stocks that fall? Yes, when the market for one reason or another gets nervous and starts thinking irrationally.

Right now the market is split in two. Anything with even the slightest connection to AI is soaring, while a lot of everything else is falling, almost regardless of whether it still has strong numbers.

It can also happen that the market punishes a company over a single bad quarter with a specific cause, because the company has run into a temporary crisis. For example a leadership vacuum or a bad launch.

When you invest as a value investor, you’ll also experience stocks falling, and you need a steady stomach when you go into it.

But if you’ve read the numbers correctly and chosen an undervalued stock with growth and profit, you can feel confident it’ll likely come back.

Once you’ve understood and chosen your strategy, you can hear a “hot stock tip” and calmly dismiss it.

You can think:

“No thanks. That’s momentum.”

Or: “No thanks. That’s a penny stock.”

Want to learn more about finding a company’s real value? Download my free e-book here. It’s all explained in there.

How Professor Aswath Damodaran invests

How Professor Aswath Damodaran invests

They call him the Dean of Valuation. 

Professor Aswath Damodaran can tell you what a company is worth.

He also calls himself a value investor, but here comes something surprising:

He doesn’t believe that value investors can beat the index.

For nearly 40 years as a professor at Stern Business School at NYU, Professor Aswath Damodaran has dedicated his life to teaching something he doesn’t think works. At least not in investing.

How does that make sense?

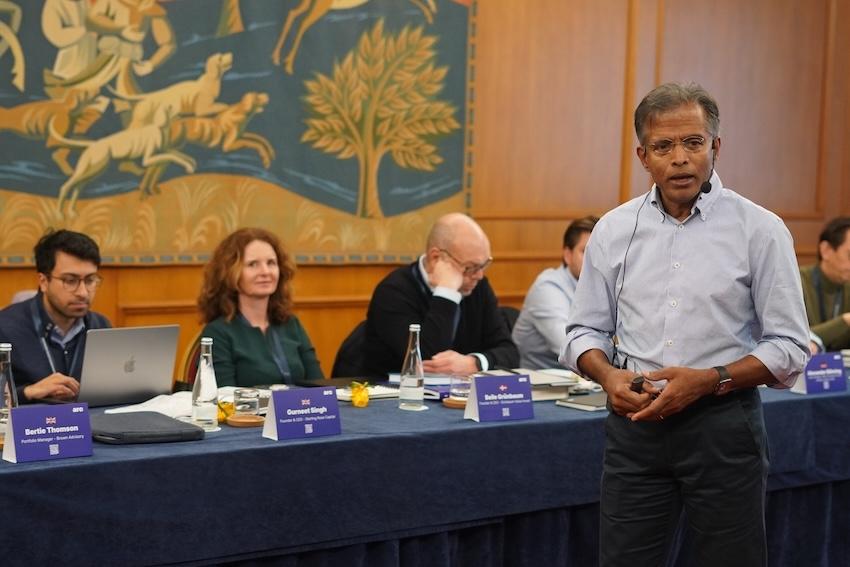
I defied storm warnings and floods to travel inland in Portugal to the medieval town of Tomar to attend a three-day course with Aswath Damodaran.

He teaches discounted cash flow, beta and risk premiums with surgical precision.

Spreadsheets. Discount rates. Decimals.

But why spend time on all that and plug it into spreadsheets if it doesn’t work?

It can, of course, be useful if you’re selling your company.

But I’m not. I’m here as an investor, and now he’s saying…wait what? 

Aswath Damodaran’s Surprise Over Dessert

I’m seated next to the professor at the introductory dinner on the first evening.

Most of the dinner is spent on polite small talk about different food cultures around the world.

From smørrebrød in Denmark to famous cod dishes in Portugal.

When dessert arrives, he drops the bomb.

“Active investors can’t beat index funds.”

Excuse me, what?

I nearly choked on the pickled fruit with cream.

We’re here to learn how to value companies so we can beat index funds. 

It’s depressing if I’ve traveled all the way to Tomar and defied storms and floods for nothing.

Am I going to sit through two days of spreadsheet talk for nothing?

I play all value investors’ trump card:

“What about Warren Buffett? He achieved extraordinary returns with the original partnership.”

For those who don’t know: From 1956 to 1969, Warren Buffett delivered an average annual return of 29.5 percent.

That’s far above the index.

The history books say so.

It’s a fact.

But he shot that down right away.

“Buffett only did better than index funds because he didn’t charge a fee,” the professor replied.

He answers with a smile. I think he enjoys teasing.

In Buffett’s original partnership, he had a compensation structure of zero in management fee. He received one quarter of the returns above 6 percent.

It’s the same way I’m compensated in Grünbaum Value Invest.

The model is often referred to as 0-6-25, and very few operate with that structure.

Most hedge funds charge 2 percent of the entire invested amount in both good and bad times. And 20 percent of the returns. 

Does Professor Aswath Damodaran invest in index funds himself?

No, he actually does invests in publicly traded companies.

Why?

“Because I think it’s fun.”

Does he beat the index? Maybe. Well, get back to that. But here is the story of how he invests. 

Here’s that story.

1. Tell a Story

One of his more uncomfortable observations, besides the one above:

We have more data than ever before.

Yet people have become worse at valuing a company.

Why?

They sit in spreadsheets adjusting decimals.

They discuss beta down to the third decimal.

They change the discount rate from 8.7 percent to 8.9 percent and feel precise.

But they can’t clearly explain:

How does the company make money?
Why will it still be relevant in 10 years?
What assumptions have to hold for this to work?

Valuation isn’t precision.

It’s structured storytelling.

You start with a story.

Then you translate it into numbers.

Not the other way around.

2. Focus on Cash Flow

At the same time, you can’t rely only on the story. 

You need to focus on earnings and cash flow.

In the investing space, there are always themes. Buzzwords.

Something that sounds good. Corporate governance. Environmental. Equality. Zero emissions. Future-proof.

You can fall completely in love with your own story about a company, especially if you top it with some buzzwords.

Aswath Damodaran’s filter for buzzwords and bullshit is simple:

Does it change the expected cash flows?

If not, it doesn’t change the intrinsic value.

That doesn’t make the topic socially irrelevant.

It just means valuation is narrower than the public debate.

3. Don’t Trust Management

Management’s forecasts are biased.

He’s very clear on that point.

Don’t blindly trust management’s growth expectations.

They have an incentive to be optimistic.

4. Be Careful With Banks, Debt, And Cyclicals

There are some categories he’s significantly more cautious about.

Banks are one of them.

Not because banks can’t be good businesses.

But the risk is difficult to assess.

To be able to value a bank, two assumptions have to hold:

That sensible people are running it.
And that regulation works.

“2008 broke my trust in both dimensions.”

He also warned against shrinking companies with high debt.

Not high debt alone.
Not declining revenue alone.

But the combination.

He called it “a crash in waiting.”

And that’s exactly how he sees it.

Cyclical companies also require extra humility.

They’re often tied to oil prices or other external factors that fluctuate wildly.

That makes them difficult to assess.

When earnings are driven by something outside the company’s control, your story becomes more fragile.

5. Remember: You’ll Be Wrong

Aswath Damodaran reminds us that we can be wrong in both the story and the valuation.

It’s usually not the end of the world, because you can achieve good returns even if you’re not completely right.

“I don’t need to be right to make money. I just need to make fewer mistakes than everyone else,” he said.

That’s a very different ambition.

Not genius.
Not perfection.

Relative rationality.

It’s about protecting your wealth.

6. He Invests in “What Can Be”

Aswath Damodaran invests in technology companies like Nvidia.

Warren Buffett historically didn’t.

Buffett’s philosophy was built around stable, mature companies with predictable earnings.

Coca-Cola, insurance companies, chocolate, running shoes.

That philosophy works.

But it rarely takes you into young technology companies, where earnings are uncertain, and the track record is short.

Damodaran pointed out that if you only invest in what’s already solid and stable, you end up concentrated in one part of companies’ life cycle.

And the economy doesn’t always reward the same part of the life cycle.

You shouldn’t only invest in what is.

You also have to be able to invest in what could become.

That requires valuing potential.

Not just the present.

It requires that you accept greater uncertainty, but in a controlled way.

That doesn’t mean you should buy hype.

It means growth also has value.

If the price is right, and the story holds.

7. No Stock Dominates

He never enters a new stock with more than 5 percent of the portfolio.

Not even if he feels a strong conviction.

And if a stock grows to more than 15 percent of the portfolio, he starts trimming.

Sometimes he’s let it run to 15 percent. But after that, he takes the top off.

For example, he’s sold half of his Nvidia position over the past few years.

Has he left money on the table? Yes.

Does he regret it? No.

His starting point isn’t to maximize the return on the individual stock.

It’s to protect the portfolio.

His wording was clear: “Don’t do anything that can threaten your lifestyle.”

When one stock takes up too much space, it’s no longer just an investment choice.

It’s a lifestyle risk.

He isn’t trying to be brilliant.

He’s trying to survive his mistakes.

8. Too Much Activity Can Kill Your Return

He warns against following CNBC and all the other news media too closely.

It creates noise, can make you nervous and make you trade too much in the stock market.

He says it quite directly:

The more active an investor is, the lower the return becomes.

Both for private and professional investors.

He only buys a few stocks a year.
Sells a few.

He has around 40 active positions.
He doesn’t check the market daily.

Investing fills his theoretical work as a professor, but the market doesn’t fill his everyday life.

And that’s intentional.

9. Companies Have to Earn Their Place

A stock doesn’t just enter his portfolio and stay there.

It has to re-earn its right to stay.

He reviews every single stock at least once a year. Some more often.

Not only because the price has moved.

But because the story may have changed.

If the assumptions no longer hold, the stock has to go.

If the price has run too far ahead of the value, he has to sell.

Buying is only half the job.

The hard part is reassessing honestly.

He says you can’t call yourself a value investor, and at the same time say you “buy and forget.”

Value investing and valuation go both ways: at purchase and at sale.

If you bought because something was undervalued, you also have to be willing to sell when it’s no longer undervalued.

A stock doesn’t have lifelong membership in his portfolio, like it often has with Warren Buffett.

10. The Goal Isn’t to Get Rich

His goal with investing is to preserve and increase his wealth.

Not to get rich.

Not to beat the market.

And that explains a lot.

It explains the 5 percent rule.

It explains why he trims at 15.

It may also explain why he doesn’t necessarily beat the index.

He himself said in an interview that it isn’t about maximum upside.

It’s about survival.

If you start with the wrong goal, he said, it distorts all your decisions.

If the goal is to get rich quickly, you take different risks.

If the goal is to beat the index at any cost, you start to overreact.

His approach is more sober.

He says that 55 percent of his stocks beat the index.

That means 45 percent don’t.

He’s okay with that.

“I invest because I like the process.”

He’s satisfied performing in line with the index.

Two Words: Concentrated Value

Beating the index is simply icing on the cake for Aswath Damodaran.

My mandate is different. 

My goal is to beat the index.

My goal is to build real wealth.

That sometimes requires concentration, conviction, and the willingness to be different.

Not for entertainment. For performance.

I once asked a billionaire how to get there.

He said: “Two words: Concentrated Value.”

I never forgot that. 

If you want to learn more about beating the index, remember to download my e-book here. 

Warren Buffett 2025: 1 Goodbye and 5 key takeaways

Warren Buffett 2025: 1 Goodbye and 5 key takeaways

Warren Buffett dropped a bombshell as he wrapped up the annual meeting of his company, Berkshire Hathaway.

He is stepping down as CEO of Berkshire Hathaway.

Why?

The Oracle of Omaha is retiring in 2025.

The man is 94 years old. No one lives forever.

For several years, he has given his successor, Greg Abel, more space and speaking time.

It’s best for everyone – shareholders, employees, and family – if it’s a controlled transition of power, not a shift after a death.

It was sudden, yet entirely expected.

And whatever the case: it’s sad.

Warren Buffett 2025 became a farewell

Warren Buffett has been our church.

The place we went to strengthen our faith in value investing.

Every year, he tells us about investing long-term and calmly.

About having patience.

About being a good person.

About doing the right thing, following our inner compass, surrounding ourselves with good people, and protecting our reputation and legacy.

Thousands of people fly to Omaha every year to hear him speak.

Or perhaps we should say: flew.

Maybe we should say it in the past tense.

Will he be there next year? At the big annual meeting in Omaha?

We don’t know yet. But probably not.

Will Greg Abel be just as wise and charming?

Well…He’s not Elvis.

No one can replace Warren Buffett. It’s the hired gun versus the entrepreneur and visionary.

This year’s meeting was the last as we know it.

Warren Buffett 2025 became the last investing class with the legend.

But wait, it’s not all over yet.

Let’s go through what Warren Buffett said this year.

Here are the five most important points from Warren Buffett 2025:

1. “Trade Should Not Be a Weapon”

It’s a bad idea to engage in a psychological trade war with nations that have nuclear weapons, some of which do not have a particularly stable leadershipo.

North Korea has nuclear weapons, and it’s hard to put the genie back in the bottle.

“We have a guy in North Korea, and if you criticize his haircut… who knows what he might do. Why should North Korea have nuclear weapons? I mean…it can’t be good thing, but they’re not going away.”

He pointed out that the U.S. has already won. A long time ago.

“We have become an incredibly important country starting from nothing 250 years ago.”

He says, it’s foolish to use trade as a kind of weapon for revenge. It would be better to build more prosperity for all nations.

“The more prosperity in the world, the safer it will feel. Our children will feel that too.”

He explains that it’s a bad strategy when a country with 300 million people (the U.S.) pushes against the world’s 7.5 billion people with a vengeful and defiant attitude.

“It’s wrong, and it’s unwise.”

2. This is Not a Crash

He brushed the current volatility in the stock market off like an ant you swat away from your hand.

“It’s not a huge move,” he said. “This har not been a dramatic bear market or anything of the sort.”

Warren Buffett has experienced much, much worse.

He explained that the stock value of Berkshire Hathaway has fallen more than 50 percent three times in history, in a very short period of time.

And it wouldn’t bother him if it happened again.

He went back to 1929 to explain that the Dow Jones fell almost 89%.

“if it makes a difference to you whether your stocks are down 15% or not, you need to get a somewhat different investment philosophy because the world is not going to adapt to you, you’re going to have to adapt to the world,” he said.

Choose Friends Who Are Better Than You


There is always a young Chinese person who stands up at the meeting and asks for career or life advice.
This year’s meeting did not disappoint.

Buffett’s followers are still hungry for common advice on how to live life.

Buffett’s best advice is to surround yourself with the right people.

People who lift you up.

Whether it’s choosing colleagues, a boss, or just friends.

It will lift both your life and career.

“You should choose friends who are better than you, because you will move in their direction.”

It’s pretty much the same thing he says every year.

But every year it hits me. It’s so simple. It’s so true.

To this advice, we can add the late Charlie Munger’s advice to actually FOLLOW the advice you’re given.

As Charlie Munger would have said: Most people nod and think it sounds reasonable, but then they do what they usually do.

Are you listening this time?

Really listening?

Because this will probably be the last time Warren Buffett tells you. 

Be Grateful Despite Setbacks

Another Chinese stockholder asked Warren Buffett how he has handled life’s setbacks.

“Charlie had setbacks, I’ve had setbacks. It’s part of life.”

Warren Buffett lost his first wife many years ago. She had cancer in her vocal cords.

As a young man Charlie Munger lost his 9-year-old son Teddy to leukemia.

Munger was also getting a divorce during that period, and lost his house, his savings, and custody of his two other children from the first marriage. 

He later shared how he walked the streets crying after the hospital visits. 

But. There’s an important “but.”

Charlie Munger continued. Didn’t give up. 

He remarried and had four children with his second wife.

He became friends with Warren Buffett, started investing in stocks, and became incredibly wealthy and a great inspiration to millions.

As he later said: Never add a tragedy to a tragedy.

Warren Buffett spoke directly to the Chinese person from Shanghai who asked for advice on getting over a “setback.”

He pointed out that he had traveled many miles to come to Omaha. From Shanghai to Omaha.
So something must be working out for him.

His health is probably okay.

And historically, a little humility and gratitude for being born now and not 100 or 500 years ago.

“If I came from the 20th generation of shepherds, I’d be bored watching sheep all day.”

He explains that you can get some bad bricks and still build a good life. As he says: We all get a bad brick every now and then. We build anyway. With gratitude.

“Look on the bright side: You’re lucky to be here today. You’re healthy. You’ve come a long way, and you have the chance to learn about something that interests you. Compare that with the life you would have been offered a couple of hundred years ago,” he said. 

5. First Thing First: Look at the Balance Sheet

Warren Buffett sprinkles out nuggets of really valuable advice on how to approach investing in stocks.

New for me was his thoughts on the balance sheet.

He explained that he places more weight on the balance sheet than on other parts of the financial statements.

The balance sheet is where the company tallies its assets and liabilities.

In other words, he focuses more on the assets than on the immediate revenues and expenses.

“I like to look at the balance sheets over an 8 or 10-year period before I even look at the income statement. Because there are certain things that’s harder to hide or play games with on the balance sheet than you can with the income statement,” he said. 

What Happens Now?

At the turn of the year, Greg Abel will take over as CEO of Berkshire Hathaway.

Warren Buffett has assured that he will not sell a single Berkshire stock.

He also says that he would like to remain involved and help the board as an advisor. After all, he is still a very large shareholder in Berkshire Hathaway.

“There might be a time when I’d be helpful, but Greg would have the tickets.”

Warren Buffett 2025 will probably be the last we hear from him.

It’s probably the last brick he’ll lay in his legacy.

If you’d like to stream the annual meeting, you can watch it here. 

How do you know if the price of the stock is reasonable? If you want to learn how Warren Buffett calculates the value of companies, you are welcome to download my free e-book here.