Warning: Undefined array key "url" in /var/www/moneyandfreedom.com/public_html/wp-content/plugins/seo-by-rank-math/includes/modules/schema/snippets/class-author.php on line 41
How to Set Up Your Investing Practice

How to Set Up Your Investing Practice

I once read a blog post that changed my life.

It was about running and maintaining the new exercise habit.

According to the blogger, all you had to do was put on the running shoes first thing in the morning.

In fact, he said you should sleep with the running shoes right next to your bed.

That was the key to your success as a runner.

Just that. So simple.

Now you’re probably wondering what this has to do with investing?

I’ll get to that. First, I just need to explain what’s so important about that simple piece of advice.

When we have to implement and maintain habits, it’s rarely the main action itself that’s difficult. It’s often all the preparation stuff around it.

It can seem so overwhelming to get stuff done. But often it really just requires five seconds of bravery. Which is the time it takes to get those running shoes on.

In other words, the biggest obstacle is getting the running gear on. Once it’s on, it’s so simple to run a few steps. Once you’ve run some steps, you might as well run a bit longer.

You won’t run if you’re wearing stilettos or Italian leather shoes.

If you want to run, you need to place those running shoes in a strategic location so it becomes a habit for you to choose them in the morning.

That’s all you have to do.

When I read this, it dawned on me that this piece of advice can be applied to almost everything else in life.

I implemented it in my eating habits. I had decided I wanted to drink fresh veggie juice every morning.

It was usually never a problem to drink the juice. It tasted good.

The biggest obstacle was getting the juicer ready and peeling the vegetables.

Sometimes small changes can make the difference.

For me, it made a big difference that I – after reading about running shoes by the bed – chose to place the juicer in a central place in the kitchen, where it was more accessible and ready to be used.

Now we come to the part about investing.

The point here is that you need to place whatever stuff you need to do your investment practice in a central location in your life.

So what are “running shoes” equivalent to in the investing world? It’s the space where you do your research and do the actual trading.

You need to prioritize creating a specific space where you can do the work.

If you always have that space set up, there is a greater chance that you’ll get it done.

In this blog post, I’ll give you my five tips to creating that space – even if you can’t set up a home office.

1. Create a Permanent Place in Your Home or Office

In the ideal world, you would have an office where you could research companies and read news.

Having a nice office with all the material you need to read and think and trade is a bit like having the juicer standing on the counter so you get right to it.

But a lot of people don’t have enough space for a home office.

You can still create a place that you know is your designated investing space.

If you’re going to sit at the dining table, choose a place other than the one where you usually eat. In this way, you can physically feel what role you’re entering when you sit down. 

I did that for years.

I would eat on one side of the table where I was facing my kids and had my back to the kitchen.

When the kids were asleep, I would clear the table and sit on the other side of the table, where I was physically a bit removed from entering the kitchen. I was now in my investing and working “seat.”

I would advise you to have your investing stuff ready in a box so you can quickly pull it out and set it up. That’s the next best thing to having an office.

2. Keep Your Investing Space Tidy and Clean

Clutter is unmade decisions.

Clutter can be things you haven’t decided whether to act on, like an invitation. Or it can be things that you don’t really know where they go. That’s also unmade decision because you haven’t decided where it should be, and it ends up being moved from one table to another.

If you surround yourself with a lot of tiny unmade decisions when you have to make big decisions, you will have a hard time focusing on what’s essential.

3. Make Sure It’s Comfortable

Yes, it sounds simple, but many people forget about the details.

You need to make sure that it’s physically comfortable to sit there.

Are your feet grounded? Do you sit up straight in the chair? Is the table the right height? How does it feel to sit down? Do you feel joy in your body, or do you prefer to avoid sitting there?

What are you looking at? A wall? Or a view?

If possible, position yourself so that you’re looking at something nice. You should either face a window or look into some kind of space. Never position yourself facing a wall.

If you’re sitting at a seat at the dining table, you want to invest in a proper office chair instead of a dining chair with a hard seat.

The little things can make a big difference in the long run.

4. Think About What You Need and How You Move

I once asked my maid where she wanted some hooks to be placed. It was fascinating observing her make the decision.

I watched her mime the movements she did when doing dishes and cleaning before she responded. She tried several spots and shook her head before choosing the right one.

She wanted the hooks exactly where she would naturally stand when she needed to use a tea towel or a rag or some oven mitts.

If there is something you need to use often, e.g., a notebook, a pen, a calculator, or some investment books, make sure it’s within reach.

It’s annoying to have to look for things or get up to get them when you’re in the flow.

5. Place Something That Inspires You In Front of You

Yoga and meditation schools often have a picture of a distant guru in India hanging on the wall.

Why? Because it’s inspiring and motivating.

It reminds them of the philosophy behind the movements they make.

You want to find something similar. Choose something that makes sense to you.

What should that be?

Ask yourself: Why do you invest? Who or what motivates you? What got you started?

Some might want a “guru” like Warren Buffett or Charlie Munger framed on the wall.

For me, my children are my biggest inspiration. I want to be bigger, better, stronger, kinder, and wealthier for them.

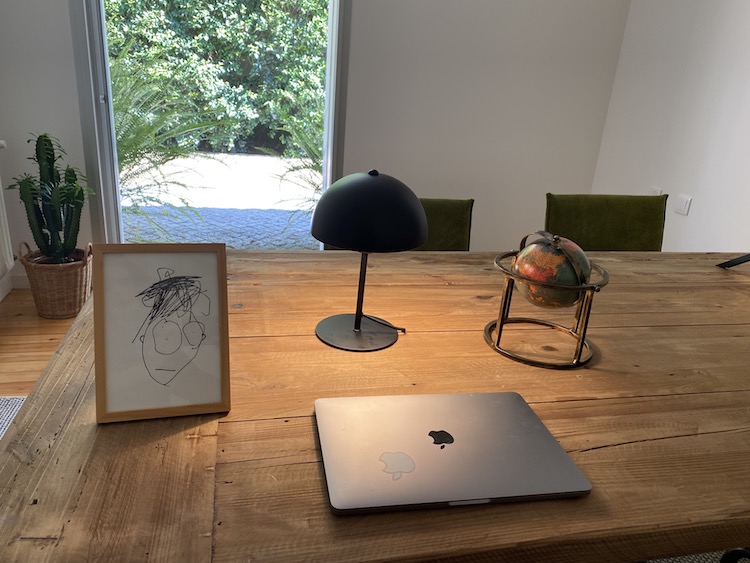
I like placing either a picture of them or a drawing made by them within view.

Currently, I have framed a drawing that my oldest son made when he was around two. It’s a peculiar drawing of me, and it reminds me that my kids are always observing me, and that they’re constantly judging the whole world based on what they see me doing.

That’s one important reason for doing “the right thing”.

The right thing in this context is to invest conscientiously, long-term, and with calm and patience.

What values ​​would you like to implement in your investments? Who or what inspires you to be that person?

In my e-book Free Yourself you can learn about investing in the stock market the way Warren Buffett does it. You can download it here.
What Happens if You Never Start Investing?

What Happens if You Never Start Investing?

It always surprises me that so many people are sitting on the sidelines of the stock market.

They want to start investing in stocks, and they participate in various Facebook groups, listen to investment podcasts, and read relevant blog posts… but they don’t buy any stocks.

How come?

They are so ready. It’s just a push of a button.

It’s probably the same reasons that prevent us from doing many other things in life.

It’s the fear that something might go wrong.

This is where people might tell you to ask yourself what’s the worst that can happen.

I think you need to ask another question.

You need to ask yourself:

“What if I never start investing in stocks? What happens then?”

Because that’s what you should really be afraid of.

I’ll try to answer that question in this blog post:

1. You’re Missing Out on a Future Fortune

The first answer is that you’re missing out on the fortune that your savings could grow into.

The other day I read about someone who had invested $50,000 over five years and made it grow into around $200,000.

I know another woman who has gradually invested all her savings since she graduated from college, and over a decade she built a portfolio of more than $2 million.

No inheritance, no money from a house or divorce. Just savings from a pretty average academic job and the magic of compounding over a decade.

So this is the first thing that will happen if you don’t start investing: you miss out on becoming a self-made millionaire.

2. Your Future

The second answer is that you’re missing out on the future you could create for yourself and your loved ones with the fortune you’re not building.

Money isn’t just money. Money is another possible future. Money is plenty of choices. Money is freedom to live a life of your choosing. 

Maybe your goal is to work less.

Maybe your goal is to make sure your children are financially safe in the future. To create generational wealth.

Maybe your goal is to be able to move to another region or country and create a new lifestyle.

Or maybe your goal is a mix of all the above: moving to another country, having the time freedom to enjoy it while feeling sure that your family is financially safe now and in the future.

I recently moved to Portugal with my two small boys. I have the freedom to work whenever I want and take breaks whenever I want. After moving, I took three months off to give us time to get settled in a new place.

I can give my family a lifestyle that most people can only dream of. Over the summer, my boys, aged 5 and 8, have learned to swim, ride a horse, play tennis, and sail. If I hadn’t invested in stocks, this wouldn’t have been possible.

3. You’ll Probably Spend the Money

If you keep your savings in cash in an account ready to spend, you’ll most likely do exactly that: spend it.

The biggest danger to your savings is spontaneous and unnecessary consumption.

Cash is too easy to use, and most people will start buying stuff and experiences they don’t really want or need, like home decor stuff or weekend getaways they are too tired to enjoy. They’ll buy it just because they can.

4. Negative Interest Rates and Inflation Also Eat Up Your Money

Even if you have the discipline to leave your savings in your account alone without spending it, your money will still slowly trickle away.

In this current market, there are negative interest rates (at least in parts of Europe), and that eats up some of your money.

Not to mention inflation will also take a serious slice of the pie.

Did you know that with an inflation rate of 4%, your money will only be worth half of that in 18 years?

Let’s say you’ve saved $100,000. It will shrink to a value of $50,000 after 18 years.What will that do to your child’s savings for a future education?

5. You Lose Confidence in Yourself

The problem with wanting to do something and not acting on it is simple:

It erodes your self-confidence.

It’s important that we do the things that we set out to do so that we can continue to trust ourselves.

If you had a friend who didn’t show up for an appointment, what would you think the next time you considered inviting him for dinner?

You might think that he probably wouldn’t show up anyway.

Maybe you wouldn’t even feel like inviting him.

Do you want that kind of a relationship with yourself?

When you want to do something and you know it’s the right thing to do, then do it. Keep your word – to others and to yourself.

Otherwise, you are undermining yourself.

Familiarize yourself with investing – read the blog posts, listen to the podcasts, take an investing course – and then get down to doing it.

Obviously, you are also going to read my e-book Free Yourself, which you can download right here.

How Do You Make a Living From Stocks?

How Do You Make a Living From Stocks?

How do you actually make a living from stocks?

What are the specific steps? Do you sell the shares?

This is a question many people ask me.

The underlying question here is also: what comprises a return on a stock? Is it just the rise in the stock price?

In this blog post, I will explain the three things that can make up your return.

I’ll also explain how I generate an income so I can pay the bills.

What Makes up a Financial Return from the Stock Market? 

Let’s begin with a definition.

According to Investopedia, a financial return is “the money made or lost on an investment over some period of time.”

Let’s break that down. How can you make money on a stock?

Here are the three factors:

1. Increase in The Stock Price

A financial return on a stock can be an increase in the stock’s market price.

This is probably what most people associate with the word “return” when it comes to stocks.

To make a living this way, you will have to sell, and this will of course reduce your remaining number of shares.

Hopefully, the remaining shares are worth so much more than when you first invested that your total wealth grows even if you sell a small portion of that portfolio.

2. Dividends

When a company makes a profit, they can choose to pay part of the profit to the owners.

As a shareholder, you are one of the owners.

When companies pay out a portion of the profits, that is called a dividend.

The dividend goes into your investment account without you having to sell the paper.

Sounds cool, doesn’t it? You don’t have to sell. You can just lean back and enjoy the ride. 

Then why not just focus on companies that pay a lot in dividends?

There are, in fact, major disadvantages to actively pursuing the so-called dividend kings.

Companies that are growing and have a large market potential ahead of them are too busy reinvesting the profits in new markets, new employees, innovation, and acquisitions. They don’t pay dividends, because that would mean missing out on great growth opportunities in the market.

The major dividend stocks typically consist of very mature companies like the Coca-Colas and Johnson & Johnsons of the world.

If you only invest in the dividend kings, you’ll miss out on great growth opportunities, and your overall return will falter.

The other disadvantage of dividends is that you have to pay tax on them. This handicaps the effect of compounding.

You can read more about the advantages and disadvantages to dividend stocks in this blog post.

3. Share Buybacks

Share buybacks are an alternative to paying dividends.

Instead of giving the money directly to the shareholders, the company may choose to use some of the profit on buying back some of their own shares.

This will cause the price of the stock to rise in the long run, because the cake (the company) will be divided into fewer slices (shares). When the cake is cut into fewer slices, each slice is worth more.

Your piece of the cake, your shares, will therefore be worth more over time if the company makes regular share buybacks.

Warren Buffett loves stock buybacks, and his company Berkshire Hathaway regularly buys back shares.

So what are the benefits of buying shares back in terms of dividends? Why is Warren Buffett so happy about it?

It’s simple.

When you receive dividends, you must pay tax on that amount. You don’t have to pay taxes when the company repurchases stocks (provided, of course, that you don’t sell the share).

This means that share buybacks don’t cripple the effect of compounding. The money can continue to grow exponentially.

But to take advantage of this, you will of course have to sell the stock at some point, and then we’re back to square 1.

You can read more about share buybacks in my blog post here.

How Do I Make a Living From Stocks?

A lot of people ask me how I do it.

Do I sell shares in order to pay the rent? Or do I pick dividend stocks?

The answer is that I do something completely different.

I do a particular kind of options trade that creates an income flow.

I follow the principles of value investing when doing these trades. I look for undervalued companies and analyze them.

The great advantage of my method is that I can live off my shares without having to sell them.

It doesn’t hurt my portfolio and doesn’t set up barriers for compound interest rates.

This is the secret method that I don’t usually talk about in my blog posts because people can get it horribly wrong if they do it uninformed.

Where did I get the inspiration for this method? From Warren Buffett himself.

It’s a public secret that Warren Buffett is one of the biggest stock options traders in the world.

Why is it a secret?

Because he doesn’t talk about options.

One thing is what Warren Buffett does and another is what he recommends his followers do.

He tells his followers to invest in an index fund. But that is pretty far from his own value investing and stock picking style.

Why does Warren Buffett never talk about his options trades?

I believe it’s for the same reason I avoid it.

I’m afraid people will google “options” and do it wrong and lose a lot of money on it. You have to know what you’re doing if you move into options – or you might put a lot of money at risk.

There is only one place where I talk about options, and that is in my courses.

I’ve been teaching this stuff for years in Danish, and more than 150 people have attended my 8-12 week long courses.

This fall I will launch my first course in English.

Make sure you’re on my email list if you want to be invited to my next webinar where I tell you about my upcoming online value investing courses. If you download my e-book, you can say yes to receiving emails.

How To Make Your Child a Millionaire

How To Make Your Child a Millionaire

“I have some money that I would like to invest for my child. How should I invest it?”

This is one of the most popular questions I hear.

The good news is that I get it.

One of my biggest drivers for investing is making my children financially independent long before they are adults.

I want to help my boys create a future where they can do whatever they want in life without worrying about money.

My 8-year-old is passionate about dinosaurs, and the 5-year-old is obsessed with space.

I know… this can change a lot of times before they grow up. But should they wish to dig for bones or study the stars, I want to make sure they can follow those passions.

I also hope they’ll never have to worry about being able to afford retirement. I’m taking care of that for them.

Is it realistic?

Of course it is. But it depends a lot on how much money you invest for them and how good you are at getting a stable return year after year.

You can help them get a good start in life for a lot less money than it will cost them in the future.

I’ll give you some examples.

If you invest $10,000 and receive an average return of 15% a year, it could theoretically become $38 million by the time your child turns 60.

For small children, you have about 20 years before they need to spend money on education abroad or housing.

Theoretically, you can invest $100,000 and turn it into $1.6 million in twenty years, if you get an average return of 15%… and don’t have to pay taxes.

You probably have two objections to this.

First of all, you could argue that 15% is unrealistic, but nonetheless it’s the goal that I myself set for my kids’ investments.

Secondly, taxes are a fact of life, and when you calculate how much the money will turn into, you’ll get a different result if you factor in taxes.

But wait. You have to read on. There are solutions.

This is where you have to be smart about how you invest for your kids. You have to use the tax-efficient ways of investing that are available to you.

The point I’m trying to illustrate with the two examples is the magic of investing for children: there is plenty of time, and compounding can work wonders.

1. Use Tax Efficient Savings Accounts for Children

Almost all countries have some kind of vehicle that allows you to invest for your child without paying taxes on the returns.

In the UK, it’s called a Child Trust Fund or ISA for children.

In the US, you can create education savings accounts such as Coverdell ESAs or 529 plans.

I’m not going to go into too much detail about how much you can contribute or what the specific rules are because it varies from country to country and sometimes from state to state.

The point here is you have to find out how you can invest for your child tax-free, because there will be a way. Most countries have a version of a tax-free account for children.

Rules you should follow when setting it up

Start as early as possible so compounding has time to work.

Set the child trust funds to run as long as possible so compounding can work its wonders while you also avoid it getting paid out while they are teenagers.

2. Use Tax-Efficient Retirement Accounts

Don’t stop at saving for their education.

Set up a retirement account for your child as well (in the US you can set up a Roth IRA for you child and in the UK you can set up an ISA).

Why would you set up a retirement account for your child?

Why wouldn’t you? For very little money, you can secure their retirement because of the wonder of compounding.

Do it as early as possible so compounding can make even a little investment into a lot of money.

3. Invest For The Long Term

There is another way to make your children’s investment more tax-efficient, and that is by investing for the really long term.

Outside the tax-efficient accounts such as the US’s Roth IRAs and the UK’s ISA, you pay taxes on capital gains.

But you only pay taxes when you sell stocks.

So what about investing in companies that you feel sure will still be a good business in 20 or even 60 years?

There are two benefits to investing this way.

Firstly, you avoid paying taxes for all that time if you keep the stock and don’t sell it. Compounding, compounding, compounding.

Secondly, you avoid the worst kind of daredevilish mistakes that many people make.

People make investing mistakes when they think they have found something that will explode in value in the near future. It’s usually too good to be true.

You make better investing decisions when you think very long term.

Overall, there are two ways you can invest. You can pick stocks yourself, or you can invest in an exchange traded fund (ETF).

I am a big proponent of the investing style called value investing. This is a method where you select individual companies whose stock prices have fallen to a level where they are on sale. You can read a lot more about how to do it in my e-book here.

However, choosing individual companies requires some work. You should look at the numbers, go through a checklist, and calculate how much the company is really worth.

If you already know that this would be too much work for you, the passive investing style is your best bet.

Here are the most important investing principles to follow when investing in ETFs:

  • Choose an ETF that follows a stock index (like Dow Jones or S&P 500)
  • Choose an ETF that is cheap in annual costs (should be less than 0.20%)
  • You can look this up on sites like morningstar.com

Learn More About Investing

If you invest in ETFs, you can’t expect the rate of return to be higher than 8% on average a year.

This means that the $10,000 you invest in your child’s retirement account will become less than a million as opposed to 38 million.

If you want to make yourself and your children financially independent, there is no way around it: you must become a good stock picker.

You must learn to follow a checklist, ask some critical questions, and think long-term.

It’s money well spent to invest in courses or a coach who can help you become a better investor.

A good place to begin is with my e-book right here. Make sure you’re on the email list so you can be invited to the free webinar I will be hosting soon.

Five Reasons Why You Should Have a Prenup Contract

Five Reasons Why You Should Have a Prenup Contract

Only a minority of couples sign a prenuptial agreement – a prenup, for short.

Even though it could have a positive impact on the relationship.

It’s a shame, because there are many benefits to being clear about what should happen financially if you separate – even if you never do.

Obviously, most people get married with the intention of staying together. It can feel awkward to enter a conversation – even before you are committing – about what needs to happen in case it doesn’t work out.

But the truth is there’s no better time to talk about it than while in love and looking forward to a future together.

It can be trickier to enter that conversation later in the marriage as it might create confusion and doubt as to whether one is heading out.

What is a prenup and what does a prenup usually contain?

It’s written agreement spouses enter into about what should happen financially if they separate.

You can decide if everything should be split 50/50 or if there should be separate ownership over certain things. You might want to protect an inheritance, a business, maybe some properties that have been passed down through generations, or just some special jewelry.

Why make a marriage contract at all?

Let’s just look at five specific reasons.

1. You Must Be Able to Talk About Money From The Beginning

It may well be that it’s uncomfortable to talk about money and when love shows up and you’re eager to demonstrate how committed you are.

But even the biggest romance will have to deal with the practicalities of life, and your relationship improves when you practice dealing with it.

Now that you’re starting a conversation about the future, it’s also a good idea to talk about other expectations, such as how you expect to divide the tasks if you have children.

2. With Separate Property, You Are More Motivated To Create Your Own Future

The American comedian Ali Wong, who is known from the Netflix series Baby Cobra and Hard Knock Wife, has said that her prenup motivated her to succeed and make an effort with her career.

She is married to Justin Hakuta, the son of a businessman who became rich by creating an octopus toy called Wacky Wall Walker that can crawl down a wall.

When Ali Wong and Justin Hakuta were to marry, Justin’s parents demanded that Ali sign a marriage contract so their son’s future fortune would be protected.

It must have hurt a little, because before they got married, Ali Wong helped her future husband pay off a $ 70,000 student loan with her own money. His future fortune was secured, but she had paid off his debt “for free.”

Yet she is deeply grateful for the marriage covenant.

“I was very motivated to make my own money because I signed a document specifically outlining how much I couldn’t depend on my husband. My father always praised ‘the gift of fear,’ and that prenup scared the shit out of me. In the end, being forced to sign that prenup was one of the greatest things that ever happened to me and my career,” she writes in her memoir Intimate Tales, Untold Secrets and Advice for Living Your Best Life.

What if you’re the one with a fortune? You might be happy in the future that you protected it.

This is what happened to singer-turned-business woman Jessica Simpson. She has written about the subject in her memoirs, Open Book.

She married pop star Nick Lachey when she was 22 and he was 31. He was older, further in his career and had more money than she did.

He actually proposed signing a marriage contract, but she got offended and rejected it, saying that they were going to be together for the rest of their lives.

However, the marriage only lasted three years, and in those three years, her career took off.

When they were about to divorce, she had a fortune of about $35 million, while his fortune was about $5 million.

She gave him whatever he wanted to get out of it. She says so in her memoir, but she doesn’t go into details as to how much she gave him. 

According to the press, he got about $10 million – almost a third of her fortune.

But what’s worse: He received the right to 1.5 % of the turnover from her beauty line.

Which brings us to the next point…

3. You Can Protect Your Assets

Jessica Simpson promised 1.5 % of the turnover from her business away to a man she was married to for three years.

I’ve heard about cases like this before.

It must be a bitter experience that a person you’ve been married to for a few years is entitled to your future income from a business that should be entirely yours because it’s your idea and your work.

It’s one thing when the parties have earned roughly the same and share everything 50/50 in the end.

It’s another matter entirely when one person is entitled to the other person’s future income.

It must be extra bitter if it’s the result of an unhappy marriage.

Jessica Simpson explains in her book that she and her ex-husband argued a lot and that she felt he was opposing her success.

Now he can reap the fruits of it forever.

A relative of mine experienced something similar.

She married a man who lived across a continent. To be with him, she resigned from her corporate job, moved to his city. To make money, she started a consulting business.

The marriage was short and not very happy.  When they divorced, he was entitled to a portion of her income from her consulting business. Ten years later, she was still paying him.

I’m not a lawyer and don’t understand the technicalities, but he must have argued that she couldn’t have built it without him and that it was an asset that should be shared.

Obviously, if you divorce, the assets will be divided. Your stock portfolio, the properties, the jewelry, risk being split between you – unless you make sure it’s protected in your prenup.

4. You Make the Decision

If you don’t sign a prenup, there will still be a prenup, but it won’t be you who decides what it looks like. It will be up to the local legislators and the interpretation of the divorce lawyers and judges.

Would you rather close your eyes and hope for the best?

Or do you want to make an informed decision?

The least you can do is familiarize yourself with the local legislation so you know which prenup you are entering if you don’t actively choose one.

5. You Protect Yourself From Someone Else’s Debt

Now we’ve talked about assets that will be divided.

But there’s also something else you need to think about: debt.

What if your partner builds up debt?

The most glaring example could be marrying a gambling addict who has built up a gambling debt. That might become your debt too.

There are other – and less dramatic – ways to build debt. It could be a company going bankrupt. It could be a bad investment.

When I was on my first maternity leave, I went for long walks with a friend who was also on maternity leave.

When you walk around with a sleeping baby in a stroller, you talk about whatever is on your mind.

It’s like getting access to another person’s inner speech… and worries.

She was worried about the debt she was burdened with from a previous relationship.

Years before, she had been in a short and unhappy marriage. She had moved on and had found herself a man who treated her well, and they had a baby.

The ex was still on her mind though. He had made a bad real estate investment during the financial crisis, and when they split up, they parted burdened with a mutual debt.

It was becoming clear to her while she was walking with the stroller that she would only have one child.

The new parents lived in a one-bedroom apartment, and they would probably continue to do so.

It hurt her that they probably wouldn’t be able to afford a second child because of the debt she had from a previous relationship.

There was barely enough room for one child in the one-bedroom apartment. Indirectly, her ex-husband helped decide how many children she could have later on.

Is It Too Late?

If you’re already married, is it too late to get a prenup?

No, of course not. You can sign one whenever you want, and you can change it later.

What’s the next step?

I’m a big proponent of getting help from the best. The next step, of course, is obvious: you need to talk to a lawyer who specializes in prenups.

How do you persuade your partner?

Explain to your partner that there is already a prenup, but it’s the local legislators who make the decisions for you, unless you create one yourself.

I would go with honesty and explain what is important to you and what benefits you see in it for your partner. After all, a prenup is not always something that puts the other at a disadvantage. It can also create security for both parties.

What points should you bring up when discussing it?

It really depends, because prenups are different.

Some people want separate property, and others want to clarify some rights to ensure that their partner is financially secure.

The most important thing is that you enter your marriage informed and well-prepared.

I’m not an expert on prenups. I am an expert on building wealth. Learn how to create a fortune by investing in stocks in my e-book Free Yourself. You can download it here.