Warning: Undefined array key "url" in /var/www/moneyandfreedom.com/public_html/wp-content/plugins/seo-by-rank-math/includes/modules/schema/snippets/class-author.php on line 41
Dividend Stocks? Here Is Your Crash Guide

Dividend Stocks? Here Is Your Crash Guide

When listening to novices and cautious shareholders, one would think that the paved road to financial freedom (and sense of financial security) lies in a very specific place:

Namely, in dividend shares.

In this blog post, I will explain exactly what dividends are and why dividend-paying stocks are not a secure investment.

I’ll also explain which companies typically fall into this category, and you will understand why they are not always the best investment.

ABC… What Is a Dividend stocks?

Let’s start at the beginning.

What exactly are dividend stocks?

On this blog, there’s room for both the investor with decades of experience and the ambitious newbie who is trying to figure it all out.

Let’s get the definition in place so everyone can join the conversation.

A dividend stock is really just a share in a company that pays dividends.

Maybe you’re asking, what’s a dividend?

When you are a shareholder, you become one of the owners of the company.

Dividends just mean that the owners get paid a part of the profits. It goes directly into your investment account as cash.

Why are Dividend Stocks Many Beginners’ Favorites?

When you start investing, you may well have a feeling that there’s a bit of an abracadabra with stocks.

Maybe shares feel a bit like play money, something that is not real (don’t worry, it’s real). 

It may seem safe and perhaps a little fascinating that real money magically appears in your investment account. It’s real cash in your pocket that can be used out there to buy ice cream and t-shirts.

It gives you the feeling that it works when you are still unsure whether those stocks are real.

And as the saying goes: A bird in hand is worth two in the bush.

But when you think about it, why is that?

What is that bird doing in that hand at all? Is it sick? Can it not fly?

That brings us to the next point…

Why You Need to Be Careful With Dividend Stocks

There are two reasons why you shouldn’t fill your portfolio up with dividend stocks.

The first reason is that dividend stocks are an extremely conservative choice, which means that your portfolio will probably stagnate.

Companies that still have a world to conquer typically don’t pay dividends because they invest to exploit their future potential. They can spend money on product development, research, expansion, hiring new talent, acquisitions of other companies, and much more.

Companies that pay a lot in dividends are often mature companies that have reached a point where they’re present in all the markets and in all the product groups that make sense to their business. You can’t expect the share price to skyrocket.

Let’s make it real with some companies that everyone knows.

Coca-Cola is known as a dividend stock. The conglomerate is in all geographic markets and sells many kinds of sodas and snacks.

It’s not realistic that they will double their revenue, but it’s realistic that they will continue to have stable growth slightly above inflation.

Amazon and Google, on the other hand, even though they are already huge, are still conquering the world. They don’t pay dividends. They are aggressively investing in new business opportunities.

Apple is a company in between. They are still growing, but they also have a gigantic cash flow and huge profits. They reinvest and make acquisitions, but they also pay a small quarterly dividend.

Compounding Is Clipped

The second reason you should be careful about going all-in on dividend stocks is taxes.

When you receive dividends, you pay taxes, and that destroys the effect of compounding.

There are other ways a company can distribute a profit and reward shareholders.

They can choose to buy shares back (also called share buybacks).

The stock price will go up because the value of the company must be distributed over fewer ownership shares – and the shareholders won’t have to pay tax on the rising stock price as long as they don’t sell it.

Warren Buffett’s company, Berkshire Hathaway, never pays dividends but regularly buys back shares for this exact reason.

When you pay taxes, it chips away at the benefit of compound interest (that’s when the money grows exponentially because your return is reinvested).

Dividend stocks aren’t optimal if you’re at the beginning of your investment journey, where the money should grow over a decade or more.

Dividend stocks make more sense if you’re going to take advantage of your financial freedom and are ready to eat off your investments.

Hopefully, the investments you make at the beginning of your journey as an investor will later pay dividends as the company matures – and then you can just sit back and enjoy it.

Where Can You Find Dividend Stocks?

Are you still keen on the idea and want to find a dividend-paying stock?

There are lots of lists of dividend-paying companies on the big internet.

You can google “dividend kings” or “dividend aristocrats”, and you’ll see the giant, international dividend-paying stocks.

Since mature companies are often international, you’ll find many great deals.

You can find one of these lists here.

Whatever you choose – dividends or not – you must make sure you choose healthy, good companies at reasonable prices.

It’s not worth it to get a return of 2 % a year in dividends if the stock price drops 50%.

You have to follow a checklist and make sure you are investing in a good company at a reasonable price – dividends or not.

You can learn more about that in my investment book Free Yourself here.
The Five Most Typical Beginner Mistakes

The Five Most Typical Beginner Mistakes

How do you invest in stocks? What do you invest in specifically?

Many newbies have probably asked a friend or googled these questions.

But there are other questions that are at least as important to ask: What should you NOT do when investing? What should you avoid investing in?

For me personally, investing in stocks has changed my life. I’ve invested myself into financial freedom. It has made it possible for me to move to Portugal with my two young boys.

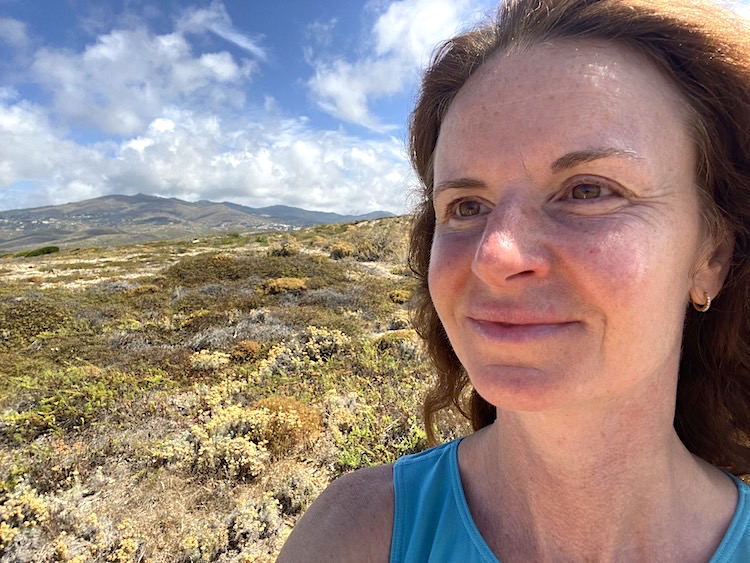
From where we live, we can walk down to the beach. There is a trail that winds through the dunes and an area with protected wildlife (as you can see in the picture).

We swim, play tennis, sail, and ride horses… a lifestyle that I previously could only daydream about from my apartment in downtown Copenhagen.

Today, I live my dream.

This dream has been possible because I have managed to make a good return on my investment over many years.

It wouldn’t have been possible if I had thrown my money into a few bad investments.

Through my blog and my investing courses, I’m in touch with many private investors. I speak with a lot of people who have jeopardized their savings, and I have recognized some patterns.

In this blog post, I will look at the typical investment mistakes private investors commit.

Mistake 1: They Only Invest in Companies From Their Own Country

There is some geographical blindness when it comes to stock investing.

The typical Danish equity investor can almost only spot Danish companies.

The German investor almost only spots German companies.

If you are from the States, it might be alright only to invest in American companies, but if you live in a country with a smaller size economy, you should consider a greater geographical spread.

Mistake 2: They Invest in Very Risky Companies

Quite a few investors put a big portion of their money into very high-risk companies such as biotech, IT companies, or startups – or even cryptos.

What’s the problem with that?

Most biotech companies don’t have a product on the market yet.

They don’t have an income and they run with a deficit.

What you’re investing in is a hope that they can develop a future medicine. That’s an extremely risky form of investment.

If you take start-ups, the problem is similar. They might have a product on the market, but they probably still run with a deficit.

You can invest in risky business if you really want to, but it should only add up to 5-10% of your total portfolio.

The bulk of your money should be invested in companies with a stable (and growing) revenue and stable (and growing) profits.

Mistake 3: They Have No Reliable Strategy

A lot of people follow investment advice from random TV show or a podcast without being critical or even researching the company.

There are several pitfalls with this way of investing:

  • You risk investing in a company that is a flop. It might go bankrupt.
  • You risk investing in an excellent company, but at the wrong time when the stock is too expensive.
  • Or you risk getting wildly nervous when the stock has natural fluctuations – and selling at the wrong time – because you haven’t researched it yourself.

Mistake 4: They Leave the Investment Decisions to The Bank

Some of the most bitter private investors I talk to are those who have let the bank make the decisions for them.

After a decade or two, it dawns on them that the money isn’t growing, and the only people who are getting rich are the money managers.

They realize – with experience and lost opportunities – what is going on.

Why doesn’t their money grow and benefit from the power of compounding?

Because the bank will almost certainly invest your money in a mixture of their own stock funds and bonds.

What’s the problem with bonds?

This is how bond works: You lend your money to governments or to companies, and you get paid for that. The problem is that in a low interest rate market, that payment is very low.

The second problem with letting the bank invest is the cost.

Maybe you think it’s cheap. Let’s say they charge you 2% to invest your money for you. That doesn’t sound expensive, right? But it is. Because it’s 2% of the entire amount invested. If they manage to make a return of 3% per year and take 2%… well, they are getting fatter than you are.

Mistake 5: They Neglect Investing in Themselves

A lot of private investors buy stocks without really knowing what they are doing.

We send our children to swimming lessons so that they can learn to swim.

We give our children driving lessons so that they can learn to drive safely.

But nowhere do we learn about managing and investing our money. It’s not something we learn about in school, and it’s not something you need a driver’s license for.

To be fair, you won’t drown or kill someone if you throw yourself into it without knowledge or guidance, but you risk smashing your financial future and freedom if you don’t follow some basic traffic rules.

As Warren Buffett says: “the best investment you can make is an investment in yourself.”

Don’t be afraid of enrolling in investment courses. It might be the best investment of your life.

You Are Your Most Important Asset

My life in Portugal wouldn’t have been possible if I had made bad investment decisions.

It wouldn’t have been possible if I had let the bank invest my money for me.

It wouldn’t have been possible if I had bought in greed or sold in panic.

It has only been possible because I have received a stable and good return over years – and that is something I have learned to create.

It’s not luck. It’s based on knowledge.

You can get the first bit of knowledge by reading my book Free Yourself. You can download it here.

How to Protect Yourself From the Threat of High Inflation

How to Protect Yourself From the Threat of High Inflation

Inflation is a threat because it erodes the value of your money.

Inflation is also a threat because it can indirectly lead to a stock market crash.

When inflation rises, the national banks around the world will eventually have to let interest rates rise to curb that rising inflation.

A hike in interest rates can cause the stock market to tumble.

If the US Federal Reserve (the Fed) raises interest rates in the US abruptly, it can actually cause a stock market crash.

We have had a taste of this several times in recent years, including in 2018 when the Fed raised interest rates four times in a row. Stock prices began to tremble… and fell sharply in late 2018. This led the Fed to lower rates again out of concern for a stock market crash, and the market calmed.

We have had low inflation and low interest rates for many years.

Why should that change now?

Because a lot of money has been pumped into the economy following the start of the COVID-19 crisis.

I won’t go into too much detail about M1 and M2 and other measures for money supply in the US to avoid making the text heavy and difficult to read. You can trust me (or google it) when I say that the Fed has pumped money into the system at a rate we haven’t seen before – not even during the 2008 financial crisis.

When large amounts of money are pumped into the system, it causes prices to rise.

Inflation in the United States has been around 2 percent for many years (on average from about 2000 until recently). This spring we saw a spike. It doubled and measured around 4 percent in May (PCE index).

Fed chairman Jerome Powell assured that the price increases are a passing problem… but he would have to say something like that to calm down the market (imagine he said the opposite – that alone could cause a crash).

Many economists are talking about the threat of rising inflation. Some even talk about possible hyperinflation.

The question I want to answer here is:

What can you do to protect yourself from inflation?

Should You Stay in Cash?

If there is an imminent threat of rising interest rates and falling stock prices, can cash be a solution?

In the short term, it’s fine to have cash so you’re able to take advantage and buy shares in the event of a stock market crash, but in the long term, cash is the worst asset group to hold.

Why? Because of the obvious fact that the value of your money will erode.

If inflation is 4 percent, the value of your money will be halved in 18 years. If it rises to an average of 5 percent, your money will be halved in 14 years. Not attractive at all.

What About Gold?

The advantage of gold is that the amount of it is limited. This means that it keeps its value over time (and even increases in value).

The problem with gold is that it’s a piece of metal that can’t invent products, employ people, or innovate. It’s not as good an asset as stocks over time.

This way of putting it comes from Warren Buffett.

He illustrated the problem with gold at the 2018 Berkshire Hathaway annual meeting.

If you had invested $ 10,000 in gold in 1942 (yes, yes, I know you weren’t alive in 1942, but Warren Buffett was), then it would have increased to $400,000 in 2018.

If you had invested the same amount in the stock market (the Dow Jones index), that amount would have become $ 51 million.

That’s a wild difference, right? A bit of an eye opener.

Why Shares Are the Best Protection

When you buy shares, you are buying a small stake in a company.

Good companies are able to protect themselves against inflation.

How?

Inflation means rising prices.

You need to find companies that can let their prices rise with inflation – or even above inflation.

Think about it.

If everything rises 4 percent, would you stop buying toothpaste or juice because they also rose 4 percent?

No, right?

We’ll continue brushing our teeth and drinking orange juice for breakfast.

Hopefully the wage level will rise with inflation anyway.

Some companies are even better at protecting themselves because their customers aren’t so sensitive to price hikes.

Take Apple’s products, for example.

The average price of an iPhone rose from $ 650 to $ 1,000 in five years.

I remember buying an iPhone 7 in 2016 and for a brief moment realizing that I was paying much more than I had previously done for an iPhone 4.

It was more or less double what my previous phone had cost.

But then it wasn’t the same phone at all. It had a better camera, improved features, and a lot more memory.

In 2020, when I bought an iPhone 11 Pro Max, I paid double what I previously paid for the iPhone 7.

I know Apple has cheaper phones than the newest Pro Max, but I didn’t want the cheapest version.

I wanted the best tool I could find, because I use the phone to make YouTube videos and Facebook Lives, among other things.

… But Don’t Invest Blindly in Stocks

When interest rates rise, there is a risk that stocks will fall drastically.

Did you know that it took 29 years for stocks to regain what they lost after 1929?

Warren Buffett’s lineup with gold and stocks would have looked completely different if he had compared their development with 1929 as a starting point.

We are in a historic stock bubble right now that makes 1929 look like a kindergarten day trip.

Shiller’s PE ratio is a measure of how expensive stocks are. In 1929 it was 30, before the crash. Today it’s 38.

This means that shares are more expensive relative to their earnings today than they were at their peak in 1929.

In other words, you can’t just put your money in an ETF that follows a stock index (such as the Dow Jones index from Warren Buffett’s example).

You risk having to wait almost 30 years for your money to recoup.

What do you do instead?

You invest intelligently in stocks.

You need to invest with an eye on how expensive a company is trading on the stock exchange, and you have to make sure that you invest when it’s cheap or reasonably priced.

You can read much more about this in my free e-book here.

Three Mistakes You Make When Haggling

Three Mistakes You Make When Haggling

The other day on Facebook, I read some tips and tricks to negotiate discounts and rebates.

There were many creative ideas and examples of white lies.

Here are some of the tricks that came up:

  • One person always said “This is above my budget” and waited for an answer.
  • One asked for a student discount… in his seventies.
  • One person said they had seen a better offer elsewhere (a white lie).
  • One stated it was too expensive and waited for a reaction.
  • Someone lied in a house trade by saying the bank only approved a smaller loan.
  • Someone else called up a hotel and asked for 5 dollars less per night.

What’s the problem with applying for discounts and rebates?

There are three main problems:

Your Focus Is on Lack of Resources

What thoughts lie behind haggling?

It’s a mindset of seeing money as a scarce resource, and it’s rooted in a mindset of lack.

That mindset is being reinforced as you haggle and tell little white lies about not being able to afford something.

It may well be that you call it a “white lie” when you tell a clerk that you can’t afford a dress, but it becomes your truth.

What do I mean by that? It’s a phrase that you say out loud, and your subconscious mind is listening in.

When you say “It’s too expensive” or “It’s over my budget”, that becomes the reality you create for yourself.

Your psyche thinks, “Aha, that’s what you want” and begins to create situations that confirm it, over and over again.

Do you use affirmations? Those small, positive phrases that we say to ourselves to affect the outcome?

It can be phrases like:

“I can do this!”

Or:

“There is abundance in my life.”

“I attract prosperity from all sides.”

With the little white lies, you create negative affirmations.

You Won’t Get the Best

The wealthiest people do the exact opposite of haggling.

They pay more for things.

They spontaneously treat their friends to dinner, they give generous tips, and they look for quality when they buy things – almost ignoring price.

They don’t like sales (have you ever wondered why there are never sales in shops like Hermès and Louis Vuitton?)

I got help from a friend when I moved to Portugal. She had lived in Portugal before and could show me the shops and help me get adjusted.

While we walked around and bought everything from drying racks to floor scrubbers, she kept saying, “Get the most expensive one”.

“Why?” I asked.

“It’s better,” she replied.

As we stood by the drying racks, I noticed how the cheap one was light in material. The expensive one was heavy and seemed better quality.

This is often the case. Quality costs more. We already know that. The best ones won’t go on sale.

After she flew back home, I continued looking for the best quality above all.

When shopping for a hair dryer, I thought of my old one that I had left behind.

I had bought it on sale in Lidl shortly after I had been fired on maternity leave (oddly enough, I still remember the price).

At the time, the focus of my life was largely on lack and fear.

That hair dryer smelled of plastic – it smelled toxic – and that smell didn’t go away with time.

When I dry my hair, the children often come over and want me to blow on them. They think it’s fun. I was often torn between denying them a little everyday fun or sending hot toxic air at a dancing and laughing toddler.

I ended up throwing it out when we moved – which is so bad for the environment too.

What did I do at the store in Portugal?

I pointed to the most expensive one they had. It felt heavy and solid. It had a place of its own in the store. Slightly raised above the others, as if it were the king of the hair dryers.

They had to order it in for me because they didn’t have it in stock.

What did it cost? I can’t remember. I didn’t care.

Does it smell like plastic?

Not at all.

It’s worth all the money because now I can enjoy my children’s excitement without fear.

You Might Lose the Trade and Hurt the Relationship

When you’re in a situation where there are several buyers, such as buying a house, a service, or a recycled item, you could lose the deal if you begin to seek out a bargain.

If you start haggling over the house, you may lose the chance to buy your dream home.

If you ask for a discount at the hairdresser, she may ask you to find another place or get annoyed with you.

Both in my business and privately, I don’t bother to go ahead with those who ask for a discount.

I only want customers who pay the full price with an attitude of excitement and gratitude. They’re the most fun customers that focus on learning and getting the most out of it.

What Should You Do Instead?

Try to focus on prosperity every day.

Focus on how much you have and cultivate an attitude of gratitude.

It doesn’t have to have anything to do with material things.

You can go for a walk and enjoy the view. Enjoy the beauty of the scenery. Enjoy the generosity of the trees. The dance of the clouds. The fresh air. The chirping of the birds.

If you quiet your mind, you can reach a place where you can feel prosperity as a strong physical force.

Some will feel goosebumps. Others a trembling sensation of joy through the body.

Try to meditate on your inner sense of prosperity for at least 15 minutes three times a day. Morning, midday, and evening.

True prosperity is so much more than money. It is an inner sense of freedom, love, generosity, gratitude, physical well-being, and wonderful relationships.

There is an infinite stream of wealth, abundance, and prosperity, and it lives within you.

When you become good at cultivating this feeling, you’ll also attract outer prosperity.

It sounds like abracadabra, but it’s not.

Your inner world and your outer world are connected. Of course they are.

As long as you focus on chasing deals and getting special discounts, you focus on scarcity and the material part of prosperity.

The good news (for those who are stuck on “lack attack”) is that daily meditations on prosperity are completely free. Not only that: It’s also 15 minutes that you don’t spend chasing deals on stuff you’ll probably never use anyway.

How does this relate to investments? It’s a perfect fit.

You’ll become a better and calmer investor when you feel inner prosperity and abundance.

You’ll be less likely to panic and sell in fear or buy in greed because you are beyond that.

Learn how to invest with my (free) e-book Free Yourself. You can download it here. 

Ten Crazy Things People Dependent on a Salary Say

Ten Crazy Things People Dependent on a Salary Say

If you are dependent on receiving a monthly salary, you have a particular way of thinking that has been encoded in you through years of schooling and socialization in the job market.

There are some special phrases, sentences and wordings that repeat themselves.

Maybe you use them too, and maybe you have never questioned your choice of wording.

Have a look at this list of ten typical phrases.

Maybe you can recognize yourself in one or more of them?

1. “It’s Not Good for My Career to ____”

You can put almost anything in here.

For example:

“It’s not good for my career to have children now.”

“It’s not good for my career to move now.”

“It’s not good for my career to take a leave to travel the world.”

People who are addicted to work tend to rob themselves of – or procrastinate on – some of life’s greatest gifts because they elevate their careers to a sacred spot.

It may not be consciously that they place a higher value on work than life.

It may be caused by an inner insecurity about what will happen and how they’ll survive and support their family if they don’t have a “career”.

But what exactly is a career?

It sounds like a thing you should have, right?

But what does that mean?

It means a job where you strive to do it well so your boss will approve and give you a promotion. But let’s be honest, it’s a job, even if it’s a fancy one.

Try to replace the word “career” with “job”.

“It’s not good for my job right now that I take a leave to travel the world.”

That sounds silly, right?

Try not to use the word “career”.

It makes you behave in a certain way that’s not really in your interest.

Avoiding the word “career” abolishes that tendency to put the world of jobs and salary on a pedestal as something almost sacred. Almost religious..

2. “There’s a Gap in Your/My Resume.”

Thinking of a resume as something fragile that unravels if you are not constantly on the go is probably one of the most foolish one of the most foolish mistakes you can make.

Nevertheless, both employees and employers often think along those lines.

You even hear the question during job interviews.

“Why is there a gap in your CV from 2009 to 2010?”

HR people ask these questions.

I think you should challenge it. Explain what you spent the time doing and emphasize what skills you got out of it.

Maybe you can even explain it on the resume so you tackle the gap question upfront.

3. “It’s Good for Your Resume”

I wish people didn’t make decisions solely based on how impressive it looks on a piece of paper.

But they do.

People take courses, do internships, and even pursue education and jobs because they think about what impression it gives on their resume.

Next time you say something about how it looks on a resume, try saying “It will look good on a piece of paper” instead.

Silly, right?

How about thinking about what skills you get from those pursuits and how you can use them in the future?

4. “I Can’t Afford to Take That Course”

The best investment you can make is an investment in yourself.

When you ask yourself if you can afford to do something, also ask yourself if you can afford not to do it.

When I sign up for a course, I always ask myself what it will take before I can earn that money back with the new skills I get.

There is usually not that much that needs to happen.

This is how entrepreneurs and investors think.

I don’t think much about what it costs – I think much more about what I can get out of it and what it can do for me and my clients in the future.

5. I Can’t Afford to Hire Help

I can’t afford cleaning help. I can’t afford an accountant. I can’t afford a babysitter.

Okay. So you say.

Have you calculated what you make in an hour?

Don’t you earn more than a cleaning assistant per hour? I should hope so.

You think like a wage slave who sees money as a fixed monthly salary.

Entrepreneurs and investors know that time is money, and that they need to buy more time by outsourcing so they have as much time as possible to focus on what they are good at.

6. “I Don’t Have Time to Pursue My Hobby”

You don’t have time to play tennis, swim in the ocean or do horseback riding (or whatever you love)?

You’re robbing yourself of the most precious thing in life … namely, life itself.

Time-poor people are the new poor.

Unfortunately, it’s very common to not prioritize old hobbies in order to have more time for a career.

7. “Do You Want to Meet for a Coffee in Week 34?”

Seriously?

Normal people don’t talk like that.

Oh, wait. All the career people do.

If you find yourself thinking in terms of ‘project weeks’ and have to plan beyond this week and next in order to schedule time for your best friend, it’s probably a sign you should kick it down a notch.”

8. “Sorry, I Can’t Tell You How Much I Earn”

It’s a shame to think like that, because you and your colleague have no opportunity to assess whether you get a reasonable salary or not.

At least be transparent with your colleagues. Transparency can put you and your coworkers in a better position when you have to renegotiate your salary.

9. “I Can’t Resign or Change Jobs Because They Need Me”

I’m sorry to tell you the harsh truth, but your workplace wouldn’t bat an eye at firing you.

You don’t owe them your life.

I made this mistake early on in my career when I worked as an office manager.

I thought the office would fall apart without me, and I postponed an internship at my dream workplace for 6 months (a newspaper).

To be in good standing with the new place, I found another guy to take the internship for the first 6 months.

Guess what. They hired him for a real permanent job – not me. He got there first.

The office management job couldn’t even find the time to write me a decent recommendation.

I still resent to this day that I wasn’t more selfish.

10. “What Am I Going to Do With All That Money?”

Some people think they will get corrupt if they have too much money.

They almost feel that it’s immoral to have more than their monthly salary in the bank account.

Where in the world does that idea come from?

Money isn’t dangerous. Money is a wonderful tool for living a great life.

Learn to appreciate money and make it grow so you have other sources of income than your paid work.

If you want to learn how to invest in stocks, you can download my investment book, Free Yourself, right here.